

Shopping season 2026 consumer survey and predictions: What shoppers expect before they buy
Survey data from 1,708 consumers across nine markets shows what shoppers expect this holiday season, from early offers to faster updates and cleaner consent.
By the time most holiday campaigns go live, shoppers have already compared prices, saved products, and decided which brands are worth their attention. So, we went straight to shoppers to see what changes their minds, what gets ignored, and how early the season starts to shape decisions.
We surveyed 1,708 consumers across nine markets: Brazil, the US, India, the Philippines, Spain, France, the UK, South Africa, and the UAE.
Three things stood out the most:
- 45% plan to spend more than last year
- 25% want holiday promotions in October or earlier
- 88% still prefer email for promotions
Before we get into what shoppers want, let’s first look at how brand messaging volumes are expected to peak during Cyber Week 2026. These platform predictions show where channel traffic is likely to grow; the consumer survey that follows explains what shoppers say they prefer.
Holiday messaging predictions 2026
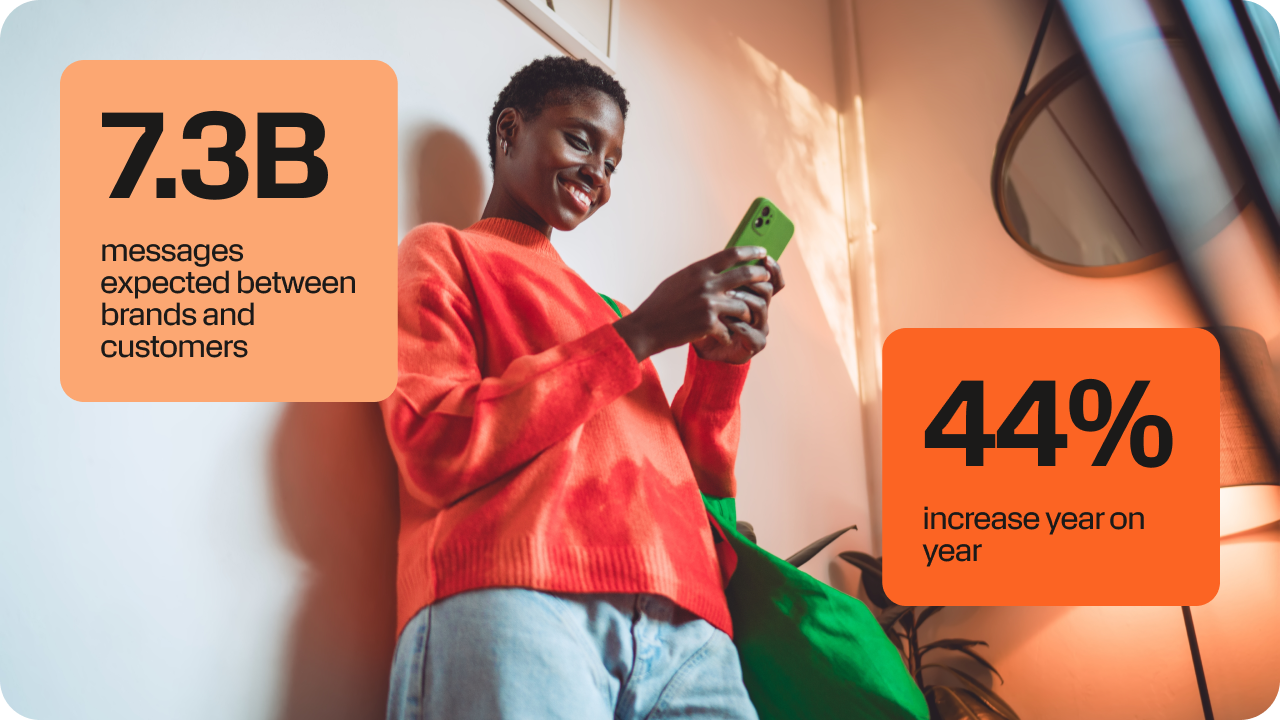
Across supported messaging channels, we expect more than 7.3 billion messages to be exchanged between brands and customers this shopping season, a 44.4% year-on-year increase.
Here’s what else our platform data predicts for the holiday season across key channels:
RCS
Compared with last year, we expect the biggest jump in traffic to come from RCS. It’s more established than it was last year and we have seen thousands of brands, many of them in retail and eCommerce, launch on the channel; and because it’s built natively into smartphones, brands can send rich, interactive messages without asking shoppers to download a separate app.
Global
- 252% expected growth on Black Friday
- 240% expected growth on Cyber Monday
Europe
- 150% expected growth on Black Friday
- 131% expected growth on Cyber Monday
North America
- 326% expected growth on Black Friday
- 322% expected growth on Cyber Monday
LatAm
- 183% expected growth on Black Friday
- 235% expected growth on Cyber Monday
Apple Messages for Business
Apple Messages for Business is especially relevant in North America, where brands are using it for rich, native commerce conversations inside messages app.
North America
- 56% expected growth on Black Friday
- 48% expected growth on Cyber Monday
Viber
Viber matters most in Europe and the Philippines, where it remains a familiar choice for brands that want a more expressive messaging experience. Compared with last year, we expect moderate growth in some markets and a much stronger Cyber Monday in MENA.
Global
- 5% expected growth on Black Friday
- 1.4x higher volume on Cyber Monday than the average day in November
Europe
- 9% expected growth on Black Friday
- 1.6x higher volume on Cyber Monday than the average day in November
MENA
- 37% expected growth on Black Friday
- 11% expected growth on Cyber Monday
WhatsApp is the most important messaging app in the mix for MENA and LatAm. Its richer format helps brands make promotions feel more useful and less generic.
Global
- 16% expected growth on Black Friday
- 17% expected growth on Cyber Monday
MENA
- 44% expected growth on Black Friday
- 61% expected growth on Cyber Monday
North America
- 8.3x higher volume on Black Friday than average day in November
- 5.75x higher volume on Cyber Monday than the average day in November
LatAm
- 20% expected growth on Black Friday
- 21% expected growth on Cyber Monday
SMS
SMS remains the workhorse channel for holiday messaging because it combines reach, speed, and reliable delivery. It is still the channel brands lean on when critical messages need to be delivered on time.
Year on year, the channel shows solid growth everywhere, with especially strong momentum in Europe and MENA.
Global
- 6% expected growth on Black Friday
- 7% expected growth on Cyber Monday
Europe
- 19% expected growth on Black Friday
- 20% expected growth on Cyber Monday
MENA
- 37% expected growth on Black Friday
- 36% expected growth on Cyber Monday
North America
- 2.5x higher volume on Black Friday than average day in November
- 2.4x higher volume on Cyber Monday than average day in November
LatAm
- 15% expected growth on Black Friday
- 26% expected growth on Cyber Monday
India
- 47% expected growth on Black Friday
- 45% expected growth on Cyber Monday
MMS
MMS is especially relevant in North America because it gives brands the reach of SMS with richer media.
Our analysts predict major boosts in MMS messaging in Europe this year compared with last year’s BFCM weekend.
Global
- 40% expected growth on Black Friday
- 43% expected growth on Cyber Monday
North America
- 40% expected growth on Black Friday
- 46% expected growth on Cyber Monday
Asia & Pacific
- 9x higher volume on Black Friday than average day in November
- 9.4x higher volume on Cyber Monday than average day in November
Email is still the default for holiday promotions because it works well for longer messages, richer detail, and broader reach. This channel also shows some of the biggest swings in holiday traffic versus last year, that is especially true in MENA and North America.
Global
- 174% expected growth on Black Friday
- 159% expected growth on Cyber Monday
Europe
- 56% expected growth on Black Friday
- 58% expected growth on Cyber Monday
MENA
- 108% expected growth on Black Friday
- 59% expected growth on Cyber Monday
North America
- 390% expected growth on Black Friday
- 537% expected growth on Cyber Monday
Asia & Pacific
- 172% expected growth on Black Friday
- 143% expected growth on Cyber Monday
Africa
- 17% expected growth on Black Friday
- 47% expected growth on Cyber Monday
LatAm
- 129% expected growth on Black Friday
- 142% expected growth on Cyber Monday
Voice
Voice remains a premium channel for peak shopping moments, with standout growth in Asia and Pacific and Africa as brands lean on live calls for high-value order confirmations and support during the biggest sales days.
Global
- 33% expected growth on Black Friday
Asia & Pacific
- 375% expected growth on Black Friday
- 262% expected growth on Cyber Monday
Africa
- 56% expected growth on Black Friday
- 64% expected growth on Cyber Monday
Now that we have looked at the predictions, let us turn to what consumers think and how they say they want to shop.
Shopper behavior trends in 2026
Shoppers worldwide told us a lot about how they expect to shop this holiday season, and their choices should heavily influence your messaging strategy.
- Start earlier than your sale date and keep the momentum going.
- Use email for reach, SMS for urgent updates, and messaging apps for richer interactions.
- Match the message to the moment so shoppers do not get the same notification three times.
Trend 1: Early is the new on-time
Each year, shoppers start to budget and plan their holiday spending a little earlier, which can help you plan when to start sending your first holiday messages so you stay top of mind without overwhelming people.
Globally, 25% plan to start holiday shopping in October or earlier, 34% in early November, and 19% the week before Black Friday. That tells us the first message needs to reach shoppers while they are still deciding when to start, not after they have already begun planning.
When do shoppers want brands to start sharing holiday promotions?
South Africa and Brazil are the earliest markets, with the Philippines close behind. India, the US, and the UK leave room for early outreach too.
| Market | October or earlier | Early November |
|---|---|---|
| South Africa | 32% | 39% |
| Brazil | 24% | 41% |
| Philippines | 28% | 39% |
| India | 29% | 30% |
| United States | 28% | 34% |
| United Kingdom | 18% | 39% |
Trend 1: CX maturity checkpoint
51% of retailers worldwide struggle to collect and organize data. Only 38% have fully integrated systems, and just 34% use orchestration platforms. Without those basics, it is hard to know when to start, who to target, and how often to follow up.
The answer is a connected setup that lets teams act on timing quickly. Start early, stay relevant, and avoid repeating the same message after the shopper has already moved on.
Trend 2: Go omnichannel, one channel cannot do all the work
Email still leads the way globally as the preferred promotional channel during BFCM (88%). That said, the rest of the survey makes it obvious that one channel cannot do all the work. 36% selected WhatsApp, 26% selected SMS, and 24% selected push notifications as their preferred channels during BFCM.
The split gets clearer once you look at the purpose of the message. For promotional campaigns, email still does the heavy lifting. For order confirmations and delivery updates, SMS marketing becomes much more important.
Which channels do shoppers want for promotions and updates?
This shows that you should stop sending one-channel campaigns. A sale alert, an order confirmation, and a delivery update are different moments. They should not sound the same, and they should not travel through the same channel.
Our SMS and email marketing guide shows why channel mix matters, while our Black Friday SMS marketing and Cyber Monday SMS marketing guides show how quickly the peak can move.
Trend 2: CX maturity checkpoint
The brands winning here are not picking a single channel and pushing everything through it. They are designing a channel mix where each message has a clear role and is delivered through the channel that fits it best. That means email for discovery, SMS for speed, and messaging apps for more interactive moments. It also means using the right automation layer so promotions do not collide with service messages.
Trend 3: Personalization needs to feel relevant
Shoppers are willing to share the signals that make deals more useful. Globally, roughly two-thirds (66%) are open to sharing product preferences, about six in ten (61%) will share items on their wish list, half (51%) are comfortable sharing their budget range, and nearly half (46%) are open to sharing past purchase history. Only a minority (7%) say they would share nothing at all.
That points to one conclusion. Shoppers will share data when they expect genuinely better deals in return, and brands need to use that data at the right time, on the right channel, through the right systems.
Which customer signals are shoppers willing to share for better personalization?
Trend 3: CX maturity checkpoint
You should not ask for everything just because you can. Use a few strong signals to narrow the offer, then use the customer data platform to put those signals to work across channels, timing, and content. That helps you keep the message short, specific, and useful.
Trend 4: Speed is part of the offer
A shopper who has already bought something is not looking for another promotion. They are looking for reassurance.
How fast do shoppers expect confirmations and support replies?
The fatigue data says the same thing in a different way. 75% unsubscribe because brands send too many messages too often. 50% point that they get to many irrelevant messages, and 36% say they get the same message on different channels.
Trend 4: CX maturity checkpoint
Instant confirmations, shipping updates, and support replies do more than reduce friction. They build trust when shoppers are at their most impatient. That is also where agentic AI earns its keep, handling the routine updates on its own and looping in a live agent, full context and all, the moment a shopper needs a human.
Trend 5: AI saves time
41% say they have used an AI assistant or chatbot to help with shopping a few times. Another 22% say they have used one frequently. On top of that, 23% say they have not used one yet but would consider it.
That tells us that shoppers are open to AI when it helps them move faster or decide more easily.
How open are shoppers to AI in the shopping journey?
The tasks they are happiest to hand over are the simpler ones, while omfort drops when the task gets closer to the purchase itself or to post-purchase support.
Which AI tasks do shoppers trust most?
Virtual try-ons through a messaging channels gives brands a useful opening for more interactive shopping experiences.
How open are shoppers to virtual try-ons in the shopping journey?
Trend 5: CX maturity checkpoint
Retailers are still figuring out how to use AI in a way that feels genuinely helpful. Use AI for comparisons, discovery, and simple service tasks first. Keep a clean handoff to a human agent when the question gets more complex. This is where AI agents can help, by handling automation, channels, AI orchestration, and live support can work together in one flow.
Trend 6: Consent has to feel obvious
The best way to collect marketing consent is a clear checkbox at checkout that is not pre-ticked. Some shoppers are also open to opting in via SMS, RCS, or WhatsApp, or through a simple toggle in a preference center when they sign up.
How do shoppers want to give marketing consent?
People are far more likely to stay engaged when they know exactly what they agreed to and how to change it later. It also makes segmentation better. Clean consent usually leads to cleaner data, and cleaner data makes it easier to send the right message on the right channel.
Trend 6: CX maturity checkpoint
The brands should ask for consent clearly, store the preference cleanly, and use it to send better, personalized messages.
Taken together, the survey points to the same direction.
- Start earlier.
- Match the channel to the moment.
- Personalize with a few strong signals.
- Use AI where it genuinely saves time.
The right channel mix still depends on the market, which is why the regional view matters.
Regional highlights
The same campaign will not land the same way everywhere. Each region has its own characteristics, some are more open to AI, and some need clearer reasons to engage. Let us see what is true for each region.
India
India is the strongest market in the survey for spending intent and one of the most AI-ready markets in the survey.
That makes India the right fit for AI-led discovery, guided shopping, and richer in-chat experiences. Brands should lead with product comparisons, deal recommendations, and virtual try-ons inside messaging, then keep the path to purchase simple. With 83% already using AI shopping assistants and 95% open to virtual try-ons, the strongest play is to make AI useful early in the journey, then let it help shoppers narrow choices and move to checkout faster.
Spending & discovery
Channels
AI & virtual try-ons
Spending & discovery
South Africa
South Africa shows a similar pattern to India in a more messaging-led way.
That makes it a strong market for brands that want to turn messaging into a browsing channel in the early stages. The best play is to lead with interactive deal catalogs, make it easy to explore offers in chat, and keep the experience simple enough to move shoppers from discovery to action.
Spending & discovery
Channels
Speed expectations
AI & virtual try-ons
Trust & fatigue
Philippines
The Philippines is one of the earliest planning markets in the survey. That means brands still have time to shape consideration before the peak, especially if they use interactive formats that help shoppers narrow choices and move faster.
Spending & timing
Channels
Speed & AI
Brazil
Brazil combines strong spending intent with a clear appetite for richer shopping experiences. That gives brands a real window to show up early, before shoppers settle on where they want to buy.
Spending & timing
Channels
About 31% prefer email for BFCM deals, but 92% say they feel overwhelmed by brand messages at least sometimes. That means brands need to keep campaigns specific, useful, and well paced, not just broad and frequent.
Fatigue
With 83% of shoppers having used AI shopping assistants a few times or frequently, and 89% open to virtual try-ons, Brazil is a strong fit for AI-led discovery, guided shopping, and interactive product journeys.
AI & virtual try-ons
United States
The US is a good fit for practical AI, product-led discovery, and timely messaging. Brands can win here when the offer is clear, the timing is early, and the message helps shoppers decide faster rather than just pushing a discount.
Spending & timing
Channels
Speed expectations
AI & virtual try-ons
Fatigue & consent
United Kingdom
The UK is even more email-led and slightly later in its planning curve.
The takeaway is that the UK still wants email first, but it responds best when brands use it to deliver clear timing, useful updates, and a specific reason to act now.
Fatigue & consent
Channels
Speed expectations
AI & virtual try-ons
Fatigue & consent
Spain
Spain shows the most cautious spending intent of the group so far but a genuine appetite for AI-assisted and messaging-native shopping experiences, alongside the strongest single-channel lean toward email among the countries covered.
Spending & timing
Channels
Speed expectations
AI & virtual try-ons
Fatigue & consent
France
France shows the most even split across shopping timing preferences of any market so far, with no single window dominating, and email remains the clear leading channel. Half of respondents chose it as their only preferred channel.
Spending & timing
Channels
Speed expectations
AI & virtual try-ons
Fatigue & consent
Brands should anchor Cyber Week outreach in email with clear early versus late segmentation, while using AI assistants and virtual try-ons as a differentiator.
United Arab Emirates
The UAE is the most receptive market of the group. Shoppers are spending more, showing up earlier, and are unusually open to AI assistants, virtual try-ons, and in-chat deal catalogs. WhatsApp shows up in the majority of preferred-channel selections, so brands should treat conversational, messaging-first experiences as the primary way to win Cyber Week in the UAE.
Spending & timing
Channels
Speed expectations
AI & virtual tryons
Fatigue & consent
Strategies for winning shopping season 2026
The strongest plans bring timing, channel choice, personalization, AI, and consent into one working system.
- Start earlier than the sale date. Shoppers are already setting their timelines in October and early November, so the first message needs to land before the season peaks.
- Match the channel to the job. Use email for reach, SMS for urgent updates, WhatsApp for richer conversations, and RCS or MMS when the offer needs more visual impact.
- Keep personalization focused. Use a few strong signals, like product preferences, wishlist items, and budget range, to make offers feel specific instead of noisy.
- Use AI where it saves time. Lead with comparisons, discovery, and simple service tasks, then hand off to a human when the question gets more complex.
- Make consent easy and obvious. Clear opt-ins lead to cleaner data, better segmentation, and fewer messages people do not want.
Infobip’s AgentOS helps teams bring every channel, profile, and workflow into one place, so they can move faster and keep marketing and service in step.
- Launch early campaigns across email, SMS, WhatsApp, RCS, and push from one platform, then adjust frequency based on real engagement.
- Personalize responsibly with unified profiles, consent-based segmentation, and context that makes each offer more relevant.
- Automate updates like order confirmations, shipping notifications, and back-in-stock alerts across any channel.
- Scale service with AI chatbots that handle FAQs, order tracking, and after-hours support, with smooth handoffs to live agents when needed.