

The fintech customer experience trends defining 2026
Explore the fintech customer experience trends shaping 2026, from agentic AI and conversational messaging to hyper-personalization, and how to deliver them.
Fintech customer experience trends are moving fast in 2026, because products are easy to copy, pricing gets matched quickly, and one bad interaction can push a customer to switch. That’s why fintech CX now decides who keeps the relationship and who loses it, and staying on top of the current trends is integral to success.
The trends below show where fintech CX is heading in 2026, and what it actually takes to keep up.
Why customer experience is the fintech battleground in 2026
The first reason is simple, fintech products are commoditizing. Core features, rates, and onboarding flows can all be matched. Once that happens, experience becomes the real differentiator.
The second reason is customer expectations. People increasingly benchmark their bank, lender, or payment app against the best digital experiences they use anywhere. Customers need to understand that a regulated financial product won’t feel quite as frictionless as ordering food, given the security, fraud, and compliance checks involved. Even so, the basics should translate (remembering preferences, suggesting next steps, and not asking customers to repeat themselves are what make the experience feel current.)
The third reason is churn. In financial services, switching often starts with one unresolved moment, not a long strategy review. A slow onboarding flow, a clumsy verification step, or an agent who lacks context can be enough to send someone elsewhere.
Then there’s the personalization gap. Customers want relevance, but too many fintechs still run on siloed data and generic segments. That’s why the execution layer matters so much. Trends without orchestration don’t change anything. You need a system that can remember, route, decide, and respond in real time.
That brings us to the trends themselves, because 2026 is less about inventing new ideas and more about finally making the existing ones work.
The fintech customer experience trends shaping 2026
Seven trends are defining fintech CX this year, and they build on each other, moving from smarter automation to conversational engagement, richer data, and the trust and continuity that hold it all together.
Agentic AI moves from chatbots to autonomous resolution
The biggest change in fintech CX is the move from scripted bots to AI agents that can actually complete work. That means more than answering FAQs, it includes helping with disputes, onboarding, payment updates, document collection, and other multi-step tasks without making the customer start over at every turn.
This is where agentic AI fits the real problem better than older chatbot models. A chatbot can guide, but an agent can act. In practice, that means the system can identify intent, pull context, take the next step, and escalate only when judgment is needed. The strongest model is human-in-the-loop, not AI-only. Customers get speed, but they still get a person when the case becomes sensitive or complex.
For fintechs, this changes the operating model. AI can handle repeat work at scale, but it only works well when it has access to unified customer data and clear guardrails. Without that, it becomes excess noise. With it, it becomes a real service layer. The point isn’t to replace people but to let teams resolve more, faster, while keeping oversight where it belongs. That leads naturally to the next trend, because once AI becomes conversational, the channel customers use starts to matter much more.
Messaging-first, conversational engagement becomes the default
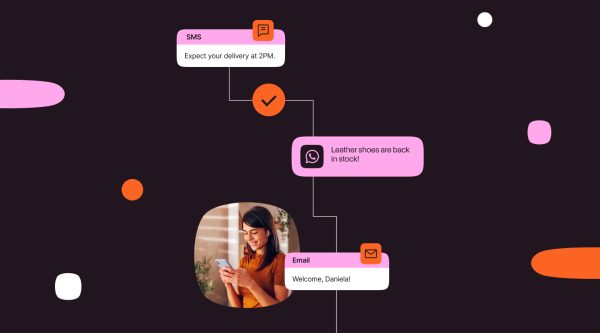
Fintech customers increasingly want to do business where they already spend time. In 2026, that means messaging channels like WhatsApp, RCS, and SMS matter more than IVR trees or app-only flows. Instead of forcing customers into forms, menus, or call queues, fintechs can keep the interaction in a thread. They can verify identity, send alerts, confirm payments, and answer questions in the same place. That reduces friction and makes the experience feel seamless and natural.
In some regions, WhatsApp is the default customer channel. In others, branded RCS or SMS still carry more weight. The point is not to choose one universal channel, but to meet customers where they already are and make the experience consistent across them.
Messaging-first CX only works when delivery is reliable, compliant, and globally scalable. That’s why Infobip’s native omnichannel reach matters here. The goal is to build the conversation layer fintechs need, especially in WhatsApp-first and emerging-market contexts.
The next trend builds on that same idea, because once engagement becomes conversational, the quality of the underlying data becomes impossible to ignore.
Hyper-personalization powered by unified customer data
Personalization has gone beyond putting a first name in an email. In fintech, it now means real-time relevance based on behavior, intent, channel preference, and context.
Many fintechs have the channels, but not the unified customer view behind them. Data lives in separate systems, so every interaction starts with partial context. The result is generic offers, repeated questions, and journeys that never quite feel coherent.
The answer is a live profile that updates as the customer interacts. If someone checks loan options three times, abandons the flow, and then returns through a different channel, the experience should reflect that, not restart from zero. When that profile is unified, personalization becomes useful instead of decorative.
Conversational CDP inside AgentOS gives teams the memory layer they need so the next message, offer, or service step is based on what the customer actually did, not what campaign research assumed. And once personalization becomes real-time, a more proactive style of communication starts to make sense.
Proactive, context-aware communication replaces reactive support
A lot of fintechs CX still waits for the customer to make the first move. However, in 2026, the better model is being proactive. Payment reminders arrive before a deadline becomes a problem. Fraud alerts appear as soon as something looks suspicious. Pre-approvals, renewal prompts, and service nudges land on the customer’s preferred channel before frustration builds. Most banks have apps where customers handle card blocks for matters of fraud, after getting a push notification of suspicious activity. Messaging should be proactive, time-sensitive interactions where the bank reaches the customer.
By the numbers: 76% of brands use WhatsApp and email sits at 90%, with voice still significant at 29% according to our recent maturity research report.
A customer who keeps using a mortgage calculator, for example, should not have to fill out the same forms twice before seeing a relevant offer. If the system already knows the intent, it can respond with timing and context that actually help.
The trend is not about sending more messages, but sending the right one at the right time, with the right channel and the right level of urgency. Of course, the more proactive you get, the more important trust becomes. That takes us to the next trend.
Trust, security, and fraud prevention become CX disciplines
In fintech, security is always a part of the experience.
Customers don’t think of verification, fraud checks, and identity controls as back-office concerns. They feel them directly when the process is clunky, slow, or repetitive. That means a poor security journey can damage CX just as much as a bad service interaction.
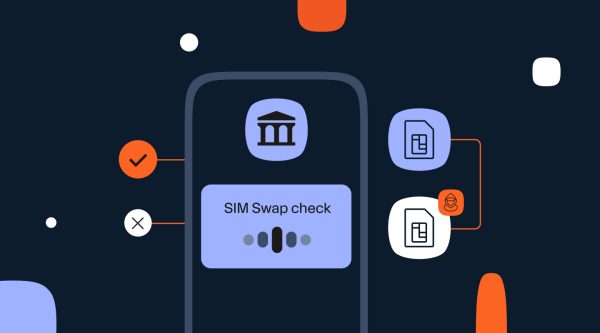
The trend for 2026 is to make trust invisible where possible. Silent verification, SIM-swap checks, and OTP fraud prevention can all reduce risk without adding friction. Done well, they protect the customer and improve their experience at the same time.
Mobile Identity and Infobip help security become part of the flow instead of a break in it. And once trust and continuity are connected, the classic hand-off problem becomes impossible to ignore.
Seamless omnichannel continuity solves the hand-off problem
Few things frustrate customers more than starting over. That is the hand-off problem in fintech CX.
A customer begins in chat, moves to a live agent, then gets told to repeat everything again. Or they start online, hit a dead end, and are pushed back to a branch or call center. Every hand-off without context adds friction and weakens trust.
The system should ideally carry context across chat, AI agents, live agents, and the app itself. If a customer has already verified identity, explained the problem, and uploaded documents, that context should follow them.
This is where Cloud Contact Center and Conversational CDP work together. One keeps the interaction connected, the other keeps the memory intact.
Compliance and data governance at global scale
Good fintech CX depends on trust, and trust depends on governance.
In 2026, regulated teams need more than messaging and automation. They need consent management, data residency, auditability, and security practices that match the markets they operate in. That applies whether they are working under GDPR, CCPA, PSD2, or other regional rules.
In the best fintech experiences, it becomes part of the design. Customers move faster because the rules are already built into the journey.
That’s also why scale matters. A platform that can operate across regions, languages, and channels gives teams more room to adapt without rebuilding every flow from scratch. For global fintechs, that is often the difference between a campaign that looks good in one market and a customer experience that works everywhere.
These trends look different across sub-verticals, though, which is why the next section matters.
Fintech CX trends by sub-vertical
The same trends show up everywhere, but each fintech vertical feels them differently. What matters most in neobanks is not what makes or breaks the experience in payments, wealth, lending, or insurance. Here is where each one should focus.
Neobanks and digital banking
For neobanks, the pressure is on onboarding and service. Customers expect fast account setup, low-friction verification, and instant help when something goes wrong. The experience has to feel mobile-first from the first tap.
That makes conversational onboarding and in-thread support especially valuable. If the journey slows down, abandonment rises quickly. The brands that win here will combine verification, service, and reminders in one connected flow.
Payments and remittance
Payments and remittance need speed, clarity, and multilingual engagement. Customers want to know what happened, when it happened, and what to do next, without waiting for a human to explain it.
In markets where WhatsApp or SMS is the dominant customer channel, the best experiences are the ones that keep the user informed without forcing app switches or call-center follow-ups.
Wealthtech and investing
Wealthtech is moving toward a blend of automation and judgment. Customers want instant portfolio alerts, clearer guidance, and help when they need to make a decision under pressure.
That makes agentic AI useful, but only when human oversight stays in the loop for high-value moments. The winning experience is responsive, informed, and easy to escalate versus fully automated.
Lending and credit
If a customer can start an application in chat, get a pre-approval update, and receive next steps on the channel they prefer, the experience feels lighter and more trustworthy. That’s especially important in credit, where uncertainty creates drop-off fast.
Insurtech
Insurtech has a different challenge. Customers often only care when something goes wrong, which makes speed and clarity the imperative.
AI-assisted first-line resolution and proactive renewal reminders can help reduce friction and improve satisfaction. The best experience is one that answers quickly, keeps context intact, and hands off to a person only when the case really needs it.
Those sub-vertical patterns point back to the same conclusion. The trends are not separate, they all need the same engagement layer underneath.
From trends to execution: The engagement layer behind fintech CX
The trends only pay off when they run on a single engagement layer, so the sections below break down the four capabilities that turn them into a working system.
A unified customer view across every interaction
Personalization, continuity, and proactive service all depend on memory. Without a unified view, every message starts from scratch.
Our Conversational CDP captures context across interactions, so the system can remember preferences, intent, and history instead of treating every session like a new customer. That shared memory is what makes the hand-off problem solvable and the personalization trend real.
Orchestrated journeys across 15+ channels
With Journey Orchestration, teams can design real-time experiences across WhatsApp, RCS, SMS, email, voice, in-app messaging, and more. The goal is not just reach, but continuity, timing, and relevance. This is how messaging-first engagement becomes more than a preference. It becomes an operating model.
AI agents and human-in-the-loop service
Agentic AI only works when customers trust it, and trust usually comes from knowing a human can step in when needed.
With Infobip’s AgentOS platform, your AI Agents handle volume and repetition, while Cloud Contact Center handles nuance, escalation, and judgment. The customer gets faster resolution without losing the human touch. That balance is what makes the autonomous resolution trend realistic for regulated industries.
Carrier-grade delivery and built-in compliance
Global reach, strong delivery, and built-in compliance are what make the rest of the stack usable at scale. For regulated teams, that also means keeping security, privacy, and data residency at the center of the design.
Fintechs already delivering on these trends
The strongest proof points come from fintechs already using conversational and AI-led engagement to improve real customer experiences.
- Mukuru is a prime example of outstanding multilingual financial services support. A 10-language chatbot that helps a remittance business serve customers across markets is exactly the kind of capability the messaging-first trend demands.
- LAQO Insurance shows how AI can handle a meaningful share of routine queries while keeping service responsive. The reported result, 30% of queries resolved by AI, is the kind of number that shows agentic service is not a theoretical answer.
- Klubi in Brazil is another strong example. Conversational AI for credit shows how lending can move away from rigid forms and toward guided, channel-native engagement. That fits the trend toward faster onboarding, better transparency, and more natural customer journeys.
- BankBazaar saw success in getting customers to download their app with 130% higher CTR. This was achieved through leveraging already popular modes of communication.
The pattern is clear. The firms that are making progress are the ones that treat CX as a connected system, not a set of separate tools.
How to prepare your fintech CX strategy for 2026
If you’re planning for 2026, start with the basics, then build the stack around them.
- Unify your customer data. If your channels and service teams cannot see the same context, personalization and continuity will both fail.
- Make messaging a core part of the journey, not an afterthought. Customers increasingly want to act inside a thread, not bounce between screens and queues.
- Deploy agentic AI with oversight. Use AI where it helps with speed and scale, then hand off to humans when the case needs judgment.
- Treat trust as part of CX. Verification, fraud prevention, and compliance should make the journey safer without making it harder.
- Think globally from the start. The right platform should help you adapt across regions, channels, and languages without creating more operational drag.
For regulated financial teams, it is also worth confirming security, compliance, and data residency requirements as part of the same conversation.
Be ahead of fintech CX trends with AgentOS
Frequently asked questions
The biggest trends are agentic AI and autonomous resolution, messaging-first engagement, hyper-personalization from unified data, proactive communication, trust and fraud prevention as CX, and seamless omnichannel continuity. The common thread is execution. Fintechs need a system that can connect data, channels, AI, and service in one place.
Agentic AI moves beyond scripted chatbots. It lets AI agents complete multi-step tasks like onboarding, disputes, or payment support, with human oversight when the case becomes complex. That matters in fintech because customers want speed, but they also want trust. The best model uses AI for volume and humans for judgment.
Because products are easier to copy than experience. If rates, features, or fees are similar, customers will stay with the provider that is easier to use and faster to trust. Fintech CX also affects retention and acquisition costs. A smooth experience reduces churn, while friction often sends customers elsewhere.
Messaging channels are taking the lead, especially WhatsApp, RCS, and SMS. Customers still use apps and websites, but they increasingly want to solve simple tasks inside a message thread. Channel preference varies by market, so the best strategy is not a single channel. It’s a connected system that can adapt to local behavior.
They need a unified customer view, real-time data, and orchestration. Personalization fails when customer data is trapped in silos or when messages are based on old segments. When the system can see behavior as it happens, it can send the next best message, offer, or service step at the right moment. That’s where unified profiles and journey orchestration matter most.
Conversational banking is the practice of managing money and getting support through natural two-way conversations across messaging, chat, and voice. It replaces some of the forms, menus, and call-center loops customers still have to deal with today. It includes both proactive engagement and self-service. That makes it one of the defining fintech CX trends of 2026.
They do it by building consent, data residency, and governance into the experience from the start. That way, personalization is based on what the customer has agreed to share, not on loose data handling. For regulated teams, trust grows when the platform is enterprise-grade and compliance-ready. The experience can be personalized without becoming risky.
Good CX reduces churn by making it easier to get help, understand next steps, and finish tasks without friction. When customers don’t have to repeat themselves or wait too long, they are far less likely to leave. Proactive communication helps too. A timely alert or reminder can prevent a problem from becoming a complaint.
Fintech CX is usually more digital, faster, and more messaging-led. Customers expect real-time responses and low-friction journeys, not long branch or call-center processes. That doesn’t mean traditional banks can’t catch up. It just means they need the same orchestration layer, unified data, and AI-led engagement that fintechs are now using.
They need a unified customer data foundation, omnichannel messaging, AI agents with human oversight, journey orchestration, and built-in compliance. Those pieces have to work together if the experience is going to feel seamless.